Yellow's Series C: The Real Moat Isn't Solar, It's The Untamed Last Mile
Yellow just pulled in Series C funding, led by an existing investor, to scale its pay-as-you-go model for essential assets across Africa. This isn't just a fintech round; it's a masterclass in building a defensible empire on the back of operational grit and unlocking untapped market potential.
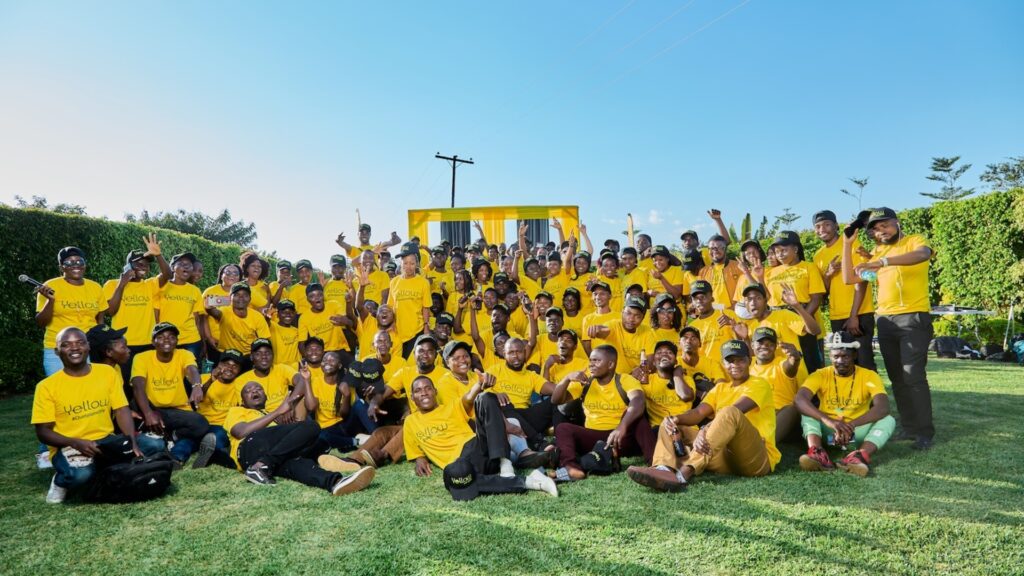
When the news hits that a company has raised a Series C, the typical founder reaction is often a mix of "good for them" and a quick scan for the numbers. But with Yellow's latest raise, led by their early backer Convergence Partners, the story isn't just about another funding round. It's a strategic beacon, shining light on an enduring, capital-intensive model that, when executed well, creates a monstrous competitive moat where others fear to tread.
Yellow, founded in 2018, isn’t selling a shiny new app. They’re providing something far more fundamental: asset-backed, pay-as-you-go (PAYG) financing for smartphones and off-grid solar systems across Malawi, Zambia, Uganda, Rwanda, Madagascar, DRC, and Nigeria. They’ve already surpassed one million customers and are aiming for ten million by 2030. That’s audacious. That’s also where the real strategic gold lies.

What Is Really Happening
This Series C isn't just growth capital; it's a testament to the fact that in fragmented, underserved markets like much of Africa, the hardest problems—like distribution and financial access—are often the most valuable to solve. Yellow isn't merely a fintech; it’s a logistics, financing, and data-driven powerhouse that's essentially building modern infrastructure, one solar panel and smartphone at a time.
The fact that Convergence Partners, an early investor, is leading this round is critical. This isn't a new firm making a speculative bet; it’s a deep-pocketed investor doubling down on a model they understand intimately. It suggests that Yellow has demonstrated solid unit economics and a clear path to scale, even in the face of significant operational complexities. For founders, this signals that patient capital, focused on fundamental pain points, can still yield immense returns.
The Human Layer: Access as a Lever
Think about the human impact. In places like rural Owerri or the bustling, yet often energy-starved, Gbagada workstations, a consistent power source or a reliable smartphone isn't a luxury; it's a gateway to economic participation. Yellow isn't just selling products; they're enabling small businesses, facilitating education, and connecting families.
By offering PAYG, Yellow shifts the power dynamic. Instead of requiring a massive upfront payment that's simply out of reach for most, they democratize access. This model fosters trust over time, turning what would be a transactional sale into a long-term customer relationship. For users, it means access to tools that improve their daily lives and economic prospects, mitigating the harsh "sapa realities" that often limit opportunity. For Yellow, it means a sticky customer base and invaluable data on payment behavior in some of the world's most informal economies.
The Culture Play: Micro-Ownership & Digital Inclusion
This move by Yellow reflects a broader cultural shift towards micro-ownership and digital inclusion, especially when traditional financial and retail systems fall short. The desire for modern conveniences – light at night, internet access for communication and commerce – is universal. Yellow taps into this by making these aspirations attainable through manageable payment plans. It normalizes high-value asset acquisition for individuals and households who might otherwise be excluded, fostering a sense of progress and participation in the digital economy. This isn't just about utility; it's about dignity and empowerment.
The Strategic Moat: Beyond the Product
The interesting thing about this story is not merely that Yellow raised Series C funding. It is actually that this raise solidifies the company’s position by reinforcing its most powerful, yet often overlooked, competitive advantage: distribution and operational density in tough markets.
The true moat isn’t the solar panels or the smartphones themselves; those are commodities. The moat is Yellow's ability to:
- Underwrite credit risk in economies with limited formal credit data, using proprietary algorithms built on millions of micro-payments.
- Manage last-mile logistics and after-sales service across multiple, geographically diverse, and often infrastructure-poor countries. This is the unglamorous, grind-it-out work that few venture-backed companies are willing to tackle at scale. It's the "no gree for anybody" execution of getting a solar kit to a remote village in Malawi and ensuring it works.
- Build a relationship of trust with customers through a consistent payment and service experience.

The Builder's Reality: Operationalizing Complexity
From a builder's perspective, Yellow’s success isn't just about a clever business model; it's a triumph of operational engineering. Imagine the complexity:
- Inventory Management: Tracking thousands of devices and solar kits across multiple warehouses, national borders, and local distribution hubs.
- Field Operations: Managing and training a vast network of agents for sales, installation, and payment collection in diverse regions, from Jos cold mornings to the Akure tech scene.
- Software Stack: A robust backend must manage millions of individual PAYG contracts, integrate with various mobile money platforms, predict churn, automate collections, and power field agent tools. The developer experience for their internal teams, ensuring reliable data flow and system uptime, is paramount.
- Customer Support: Handling queries and technical issues for a geographically dispersed customer base, often with limited digital literacy.
This is not a lean, asset-light startup. This is a capital-intensive, operationally heavy machine, and that very weight becomes its defensive strength. Competing with Yellow isn't just about matching their tech; it's about replicating years of on-the-ground learning and network building.
FOUNDER DIRECTIVE / ADVISORY SECTION
The Short Answer
Yellow's Series C is a strategic validation of the PAYG model for essential services in Africa, underscoring that owning the last-mile distribution and financing rails in tough markets creates an almost unassailable competitive advantage.
What Is Really Happening
Yellow isn't just selling smartphones or solar panels; they are building a vital financial and logistical infrastructure layer that provides millions with access to fundamental modern utilities. This isn't a quick-win SaaS play; it's a long-term, capital-intensive grind that, when executed correctly, yields an incredibly sticky customer base and deep insights into underserved consumer behavior. The repeat investment from Convergence Partners is the clearest signal of confidence in this complex, yet highly rewarding, strategy. They see Yellow not just as a product provider, but as a future platform for a multitude of services built on that trusted payment rail and customer relationship.
The Assumption I'd Challenge
The assumption I'd challenge is that Yellow's primary business is "off-grid solar" or "smartphone sales." While these are their product vectors, their core business is actually credit scoring, last-mile asset financing, and data acquisition in high-friction, underserved markets. The products are the means to an end: building a ubiquitous payment and distribution network, and a deep understanding of customer financial behavior where formal records are scarce. Don't confuse the vehicle with the engine.
The Strategic Options
For a founder looking at similar market gaps:
- Deep Vertical Integration (The Yellow Play): Own the entire value chain – product sourcing, financing, distribution, installation, and after-sales. This demands significant capital, operational expertise, and patience. The upside is maximum control and maximum moat.
- Platform & Partnership Model: Focus on building the financing and distribution intelligence, then partner with various hardware providers. This can reduce capex but requires robust partner management and potentially sacrifices some margin or product control.
- Niche Geographic/Product Specialization: Dominate a smaller, specific region (e.g., just Nigeria, or even just Lagos & Ibadan) or a single product category (e.g., only water purification systems via PAYG) to achieve hyper-efficiency and prove unit economics before contemplating broader expansion.
My Recommendation
For a new founder entering a similar space, my recommendation would be Niche Geographic/Product Specialization with a lean towards the Platform & Partnership Model initially. Trying to replicate Yellow's scale and vertical integration from day one is a recipe for disaster. Focus on proving exceptional unit economics, high customer satisfaction, and a robust payment collection rate in a concentrated area first. Let others handle manufacturing; perfect the distribution and financing.
What I Would Do Next (If I were Yellow's founder)
- Double Down on Data Science: With a million customers and growing, the richness of payment and usage data is immense. Use it for hyper-personalized upsell opportunities (e.g., offering micro-insurance, extended warranties, or even educational content based on smartphone usage patterns). Refine credit scoring models to reduce risk and allow for faster product approval.
- Operational Automation: Identify the top 3-5 operational bottlenecks (e.g., agent onboarding, inventory reconciliation, specific repair workflows) and invest heavily in tech solutions to automate or streamline them. This will be key to scaling from 1M to 10M customers without spiraling costs.
- Explore Service Bundling: Now that customers trust Yellow for essential assets and payments, consider bundling additional digital services – affordable data plans, local content subscriptions, or even micro-lending for small business needs – directly onto their payment platform. Leverage that existing payment rail.
What Would Change My Mind
My confidence in Yellow's model would waver if:
- Massive Regulatory Shifts: Governments in their key markets suddenly impose prohibitive tariffs on imported assets, or enact regulations that cripple micro-financing or PAYG models.
- Widespread Infrastructure Leapfrogging: If grid electricity suddenly becomes universally reliable and affordable across their markets, or if major telcos drastically cut smartphone prices and offer their own robust, widely accessible micro-financing, Yellow's value proposition would be fundamentally eroded.
- Operational Collapse: A significant, sustained increase in default rates or a critical breakdown in their logistics and customer service networks, indicating that their operational density can no longer keep pace with their scale. This is the hardest part of their business and the most vulnerable point.

Related from Venture
Let's build your next big product.
Accepting project-based freelance, remote engineering roles, and hybrid positions.